Breaking: SPEAKER JOHNSON DROPS ALARMING DETAILS DURING LIVE TV APPEARANCE
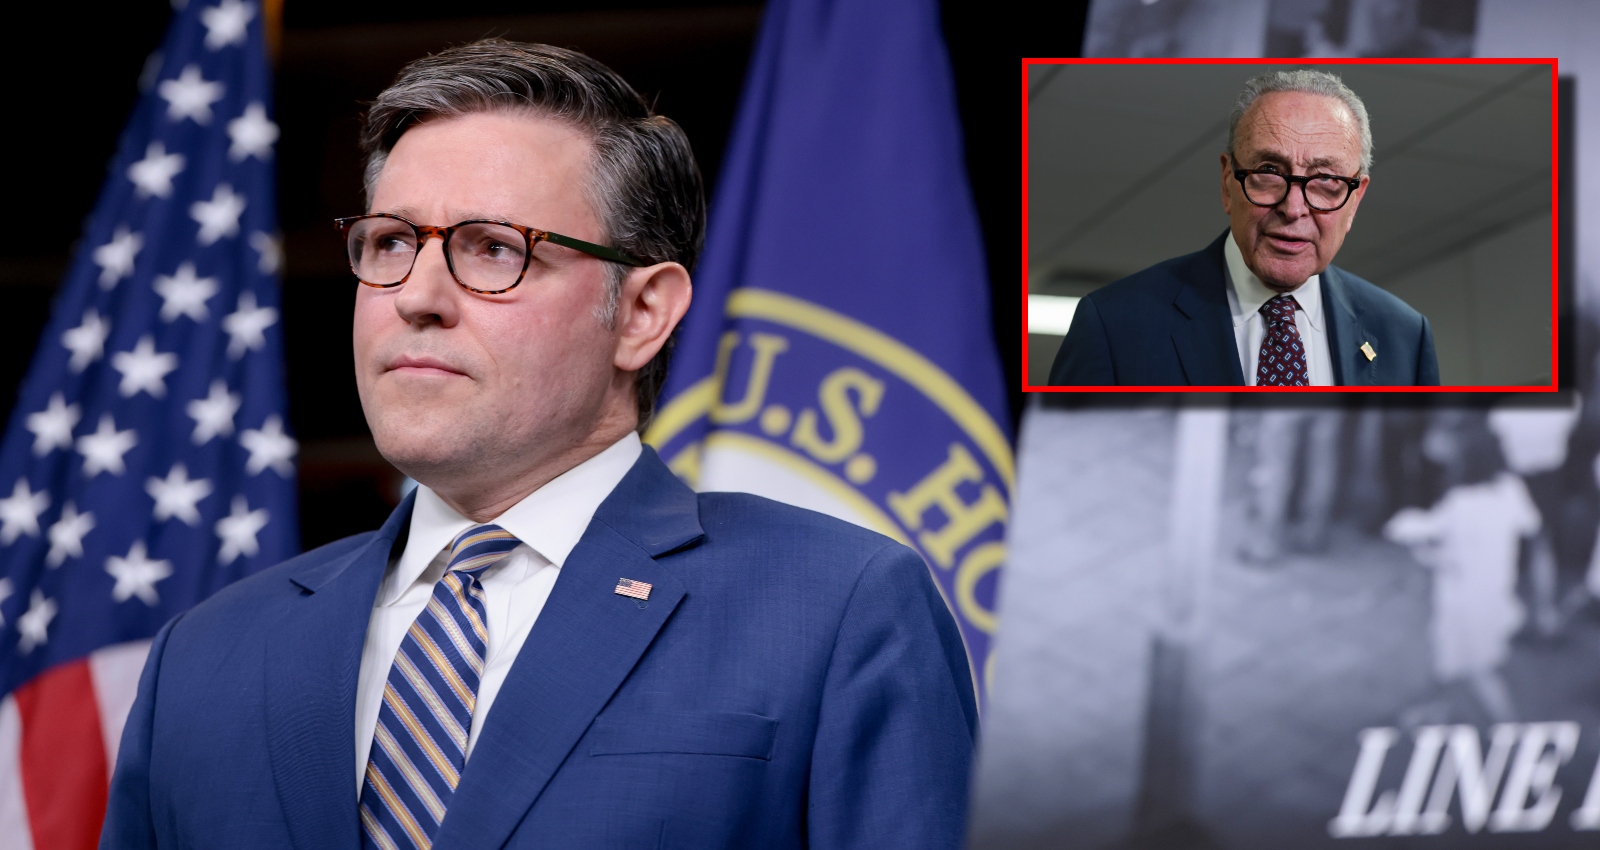
Johnson Says Democrats Are Taking Credit for Trump Tax Cuts—But Their Votes Were on the Entire Package
House Speaker Mike Johnson has a simple argument for Democrats now promoting pieces of President Donald Trump’s signature tax law.
They voted against it.
Now, he says, some of them want credit for parts of it.
One year after Trump signed Public Law 119-21, Johnson is highlighting Democratic lawmakers who opposed the massive Republican reconciliation package but have since supported, promoted or proposed expanding individual tax provisions contained inside it.
The political contrast is real.
Every House Democrat voted against the final legislation on July 3, 2025.
The House approved it 218-214, with 218 Republicans voting yes, all 212 Democrats voting no and two Republicans joining Democrats in opposition.
The Senate vote was even closer.
H.R. 1 passed 50-50 on July 1 after Vice President JD Vance cast the tie-breaking vote.
No Democratic senator voted for it.
Trump signed the measure into law on July 4.
The Treasury Department and IRS now publicly refer to the law and its tax provisions as the “Working Families Tax Cuts.”
That voting record gives Johnson the foundation for his attack.
But it does not completely settle the argument.
The reason is straightforward.
Congress did not hold separate final votes on “No Tax on Tips,” “No Tax on Overtime,” Trump Accounts, Medicaid changes, SNAP changes, business tax provisions and every other major element of the legislation.
Lawmakers voted on the entire package.
That distinction is now at the center of the political fight.
Johnson argues Democrats cannot credibly celebrate individual benefits created by legislation they unanimously opposed.
Democrats counter that opposing a sprawling reconciliation bill does not mean opposing every policy contained in it.
Both claims describe part of what happened.
The question is which part voters consider more important.
The law itself contains several tax provisions that Republicans are aggressively promoting ahead of the 2026 midterm elections.
One of the most visible is the new deduction for qualified tips.
For tax years 2025 through 2028, eligible workers may deduct up to $25,000 in qualified tip income.
The deduction begins phasing out when modified adjusted gross income exceeds $150,000 for an individual or $300,000 for married couples filing jointly.
Despite the political shorthand “No Tax on Tips,” the provision is a federal income-tax deduction rather than a blanket elimination of every tax that can apply to tipped income.
Eligibility rules also determine what qualifies as a tip and which occupations may use the deduction.
The overtime provision works similarly.
For tax years 2025 through 2028, workers can deduct up to $12,500 of qualified overtime compensation, or $25,000 for married couples filing jointly.
But it does not mean all overtime wages are automatically tax-free.
The deduction generally applies to the premium portion of overtime required under the Fair Labor Standards Act—the additional amount above a worker’s regular rate, such as the extra half of traditional time-and-a-half compensation.
That limitation later became politically important.
Some workers, including employees covered under other labor rules or collective bargaining agreements, can receive overtime compensation that does not fit neatly within the law’s FLSA-based definition.
That gap is one reason a bipartisan group that includes Democratic Reps. Emilia Sykes, Steven Horsford and Tom Suozzi later introduced legislation to expand eligibility.
Johnson sees that as evidence supporting his argument.
Suozzi voted against H.R. 1.
So did Sykes and Horsford.
Yet all three later backed legislation designed to make one of the law’s most politically popular tax breaks available to additional workers.
Republicans can accurately say those lawmakers voted against the legislation that created the original deduction.
What is harder to say is that their vote proves they opposed the overtime deduction itself.
Their later legislation suggests the opposite.
Sykes’ bill does not repeal “No Tax on Overtime.”
It attempts to broaden it.
The distinction is even clearer in Nevada.
Sens. Catherine Cortez Masto and Jacky Rosen and Reps. Dina Titus, Susie Lee and Steven Horsford all opposed the Republican reconciliation package.
But Nevada has an unusually large hospitality and service economy, making the tips provision particularly relevant to their constituents.
In August 2025, all five Democrats wrote Treasury Secretary Scott Bessent asking his department to address what they described as implementation problems with the new deduction.
They asked Treasury to make the provision work more effectively for Nevada workers.
Among other requests, they wanted clearer occupational eligibility rules, accommodation for certain gaming-industry tip arrangements and treatment of auto-gratuities and suggested tip amounts.
They also asked for broader treatment of some married taxpayers.
That is the example Johnson wants voters to notice.
The lawmakers opposed H.R. 1.
Then they wrote the Trump administration asking it to implement one of H.R. 1’s benefits more broadly.
But the history is more complicated than Democrats suddenly discovering that they liked tax relief for tipped workers.
Nevada Democrats had supported separate tip-tax legislation before the reconciliation package became law.
Cortez Masto’s office noted that she had already helped introduce the bipartisan No Tax on Tips Act.
The Senate itself passed a separate No Tax on Tips Act by unanimous consent in May 2025, before the final reconciliation law was enacted.
So in Nevada’s case, opposition to H.R. 1 cannot simply be translated into opposition to the concept of reducing taxes on tips.
Several Democrats supported that concept independently.
Their disagreement was with the broader package in which Republicans ultimately enacted it.
Sen. Ruben Gallego of Arizona provides another example—and also illustrates why Johnson’s argument needs careful wording.
Johnson’s office has cited Gallego for embracing policies that originated in the Republican law after voting against the package.
One example is Trump Accounts.
The law created a new type of tax-advantaged investment account for children.
Trump Accounts themselves are permanent, while a special federal pilot program provides a one-time $1,000 Treasury contribution for qualifying U.S.-citizen children born from January 1, 2025, through December 31, 2028.
Gallego later introduced legislation to rename the accounts “American Dream Accounts,” make the $1,000 government contribution permanent and index it to inflation.
That plainly builds on a policy created by the Republican reconciliation law.
But again, Gallego’s proposal is not simply taking credit for passing H.R. 1.
It changes the program.
He wants to remove Trump’s name, alter enrollment and extend a federal contribution that is currently limited to a four-year birth cohort.
Johnson’s office also cited Gallego on “No Tax on Tips.”
Here, however, the record requires more caution.
Johnson’s July statement said Gallego had introduced a bill to make “No Tax on Tips” permanent.
But the Gallego measure linked by Johnson’s own office is the No Tax on Large Party Tips Act.
That bill does something different.
It would expand the existing deduction to include certain automatic gratuities and recommended tips.
Gallego’s own announcement explicitly acknowledges that the current deduction expires in 2028.
Rather than saying his bill makes it permanent, he argued that while the deduction exists, more workers should be able to benefit from it.
That makes Johnson’s broader political argument stronger than that particular factual example.
Gallego did vote against the Republican package.
He did later propose expanding one of its tax benefits.
But the available legislation cited by Johnson does not establish that Gallego proposed making that tips deduction permanent.
Those details matter because the argument is increasingly becoming a fight over who gets political ownership of popular provisions.
Johnson’s position is that ownership belongs to the lawmakers who supplied the votes necessary to enact them.
“With their unanimous opposition to the Working Families Tax Cuts,” Johnson said, Democrats voted against provisions including tips and overtime deductions, the Child Tax Credit, rural health funding and children’s investment accounts.
Republicans have a powerful numerical fact behind that message.
Had Democrats’ votes alone determined the outcome, H.R. 1 would not have become law.
There were zero Democratic votes for the final House legislation.
There were zero Democratic votes supplying the Senate majority.
Vance had to break the 50-50 Senate tie.
Without Republican votes, the package—and therefore the tax provisions enacted through it—would have failed.
But Democrats have a different numerical argument.
The bill was not simply a collection of tax reductions.
It also made enormous changes to federal spending and benefit programs.
The Congressional Budget Office estimated that Public Law 119-21 would reduce direct federal spending by approximately $1.1 trillion over the 2025-2034 period while reducing federal revenues by approximately $4.5 trillion.
Using CBO’s January 2025 baseline, the agency estimated that the law would increase cumulative federal deficits by about $3.4 trillion over that period.
That estimate is frequently cited by Democrats.
But even the deficit debate has a baseline dispute behind it.
Under a different “budget enforcement” baseline used during Senate consideration, CBO calculated that the enacted law would reduce deficits by approximately $366 billion over 2025-2034.
The difference largely reflects how the baseline treats the expiration of tax provisions and other assumptions—not two different versions of the law.
That is why Republicans and Democrats can cite dramatically different deficit numbers while discussing the same legislation.
Under a current-law-style baseline in which expiring tax cuts are assumed to disappear, extending them counts as lost federal revenue.
Under a baseline that assumes those policies would have continued anyway, the same extension has a much smaller apparent budgetary cost.
Neither framing changes what individual taxpayers actually claim on their returns.
But it changes the political description of what the law costs.
The distributional effects are also mixed.
CBO estimated that American households overall would see an increase in resources available to them under Public Law 119-21.
But those gains would not be evenly distributed.
Households toward the bottom of the income distribution would generally see resources decrease, while households in the middle and upper portions of the distribution would generally see increases.
CBO estimated roughly $3.3 trillion in higher household resources from federal taxes and cash-transfer changes over 2026-2034.
At the same time, it estimated about $900 billion in reduced federal and state in-kind benefits, largely because spending on Medicaid and the Supplemental Nutrition Assistance Program would be lower.
That helps explain why a Democrat could support a tips deduction and still vote against the entire law.
A lawmaker could conclude that a $25,000 deduction for qualified tips is good policy while believing that reductions affecting Medicaid or SNAP are unacceptable.
Or a lawmaker could support the Child Tax Credit while opposing the deficit impact.
Or favor overtime relief while rejecting other tax changes.
Congress regularly forces lawmakers to make that type of package-level choice.
Republicans nevertheless argue that political accountability has to follow the final vote.
If a lawmaker votes against a bill, they say, that lawmaker voted against the package that actually became law—including its popular provisions.
That argument has become easier for Republicans to make because the tax provisions are no longer theoretical.
Americans have now filed returns under the law.
Treasury says taxpayers claimed more than $82 billion in individual relief tied directly to the Working Families Tax Cuts through the April 2026 filing deadline.
The administration says more than 7.5 million filers claimed the qualified-tips deduction, with an average deduction exceeding $7,000.
More than 29 million filers claimed the overtime deduction, according to Treasury, with an average deduction above $3,100.
Treasury also says nearly 40 million families claimed the enhanced Child Tax Credit.
More than 5.5 million Trump Accounts had been opened by the time of its June analysis, with approximately 1.4 million eligible for the federal $1,000 pilot contribution.
Those are administration figures.
They are useful for measuring how often particular provisions were claimed, but some of Treasury’s broader descriptions are inherently political.
For example, Treasury says 97 percent of filers received a tax cut compared with what they would have owed if the expiring provisions had not been extended.
That comparison is real, but the baseline is essential.
It does not mean 97 percent of taxpayers necessarily paid less tax in 2025 than they personally paid in 2024.
It means Treasury compared their liability with a counterfactual in which expiring portions of the 2017 Tax Cuts and Jobs Act were allowed to lapse.
That distinction is important when Republicans describe the law as preventing a massive tax increase.
Many major provisions of Trump’s 2017 tax law were scheduled to expire.
Public Law 119-21 prevented many of those expirations.
From the Republican perspective, allowing them to expire would have constituted a tax increase.
From another budgetary perspective, extending temporary tax provisions creates new revenue losses relative to current law.
That same disagreement appears in descriptions of the Child Tax Credit.
Johnson calls the law’s credit “doubled.”
Treasury similarly describes it as permanently doubled and expanded.
The history requires context.
Trump’s 2017 tax law had previously raised the maximum Child Tax Credit from $1,000 to $2,000.
Public Law 119-21 prevented that structure from expiring and increased the maximum credit to $2,200 beginning in 2025.
So describing the credit as “doubled” refers to preserving the increase relative to the pre-2017 $1,000 level.
The new law itself did not suddenly double the immediately preceding $2,000 credit to $4,000.
It raised it to $2,200 and preserved major elements that otherwise would have expired.
The rural-health provision presents another example of how the same legislation contains policies with very different constituencies.
Public Law 119-21 established the Rural Health Transformation Program, a $50 billion initiative administered through the Centers for Medicare & Medicaid Services.
CMS says all 50 states are receiving awards through the program, with first-year 2026 awards averaging about $200 million per state.
Republicans point to that program when Democrats criticize the law’s healthcare effects.
Democrats point back to the broader Medicaid reductions.
Both provisions exist in the same statute.
That is exactly why the political argument cannot be reduced to a single sentence.
Johnson is correct about the final vote.
Congressional Democrats did not provide votes to enact H.R. 1.
Every House Democrat voted no.
The Senate Democratic caucus did not provide the vote needed for passage.
Republicans passed the legislation and Trump signed it.
Johnson is also correct that some Democrats have subsequently supported policies that overlap with or expand provisions created by that law.
Suozzi, Sykes and Horsford backed broader overtime eligibility.
Nevada Democrats pressed Treasury to improve implementation of the tips deduction.
Gallego proposed expanding the treatment of certain gratuities and extending the federal contribution connected with children’s accounts.
What goes too far is treating those facts as proof that the lawmakers secretly supported the entire Republican law when they voted against it.
Their public positions show something narrower.
They support some of its provisions.
They oppose others.
And in several cases they want to rewrite individual provisions rather than simply preserve them unchanged.
That is not an unusual legislative position.
A member of Congress can oppose a 900-page reconciliation package while supporting one section of it.
But Republicans have an equally straightforward political response.
Individual provisions do not become law by themselves simply because lawmakers say they like them.
The actual legislation needed enough votes to pass.
Democrats withheld theirs.
Republicans supplied them.
That is the tension Johnson is trying to turn into a midterm message.
Republicans want voters who claimed the tips deduction, overtime deduction, Child Tax Credit or other benefits to associate those savings with Trump and the Republican congressional majority.
Treasury’s first-year data gives them millions of taxpayers to point toward.
Democrats want voters to evaluate the law as a whole.
They are likely to focus on Medicaid, SNAP, distributional effects and deficits while arguing that supporting an individual tax break does not require accepting every other provision Republicans attached to it.
CBO’s analyses give that argument factual substance as well.
The agency projects both substantial tax-related gains for households and substantial reductions in in-kind benefits, with the effects varying significantly by income.
So the dispute is not really over whether Democrats voted against Trump’s legislation.
They did.
Nor is it over whether some Democrats now support individual policies contained in it.
They do.
The unresolved question is what a vote against a massive package should mean politically.
Johnson wants it to mean Democrats voted against every benefit Republicans can identify inside the law.
Democrats want it to mean they rejected the overall balance of tax cuts, spending reductions and other policy changes while remaining free to support provisions they consider worthwhile.
Neither side needs to invent a voting record to make its case.
The disagreement is over how that voting record should be interpreted.
And with the 2026 midterms approaching, that distinction matters.
Republicans now have a law producing tax deductions that millions of people have actually claimed.
Democrats have a law they can attack for its effects on healthcare, food assistance and the federal budget.
The same statute supplies ammunition to both parties.
Johnson’s strongest argument is therefore narrower than saying Democrats opposed every tax cut they now support.
They opposed the only package that actually enacted those tax cuts.
The Democrats’ strongest response is equally narrow.
May you like
A vote against that package does not prove they opposed every provision inside it.
Voters will now decide which distinction matters more.